How to check your credit score for free as a credit cardholder

How to check your credit score for free as a credit cardholder

Understanding Your Credit Score

Your credit score is a crucial financial instrument that significantly influences various aspects of your financial life. It not only determines your eligibility for loans and credit cards but can also affect job prospects, as some employers perform credit checks as part of their hiring process. While numerous services provide credit scores for a fee, a surprising number of free options are available to credit cardholders, courtesy of financial institutions and other credible sources. This article provides a comprehensive exploration of how you can access your credit score free of charge and maintain a good credit standing over time.

Accessing Your Credit Score Through Your Credit Card Issuer

Many credit card issuers offer the invaluable benefit of free credit score access to their customers. This benefit is designed to keep cardholders informed about their credit health. The service is accessible through the issuer’s website or accompanying mobile app, making it easy and convenient to check your score regularly. For instance, Discover provides the Discover Credit Scorecard, which allows users to check their FICO score at no cost. Similarly, Capital One offers a service known as CreditWise. These tools not only display your credit score but also provide insights into factors affecting it.

To access your credit score through your credit card issuer, follow these straightforward steps:

  • Log into your credit card account via the issuer’s website or mobile application.
  • Locate a section titled credit score, financial insights, or my credit.
  • Follow the link provided to review your credit score and related details.

This approach is beneficial for regular monitoring of your credit standing, which can empower you to make informed financial decisions and manage debts more effectively.

Using Free Credit Monitoring Services

Beyond services offered by credit card companies, several independent platforms provide free access to your credit score and offer valuable insights into your credit history. These platforms include Credit Karma and Experian, both of which are popular for their user-friendly interfaces and comprehensive analysis of credit health. These platforms often provide additional features such as credit alerts, which notify you of changes in your credit report, and recommendations for improving your credit score.

To benefit from these services, you need to:

  • Visit the chosen service’s website.
  • Register by providing personal information such as your name, address, and Social Security number to establish an account.
  • Access your credit score and explore the array of tools available, such as report analysis and personalized credit improvement tips.
Requesting a Free Annual Credit Report

Alongside accessing your credit score, you have the right to request a free credit report annually from each of the three primary credit reporting agencies: Equifax, Experian, and TransUnion. This entitlement is facilitated by the website AnnualCreditReport.com. The credit report provides detailed insights into your credit activities, including your borrowing and repayment history, which can be instrumental in spotting irregularities or identifying areas for improvement.

To request your free credit report:

  • Navigate to the official Annual Credit Report website.
  • Complete the provided form with basic personal information necessary for report retrieval.
  • Select from which credit bureau you wish to obtain your report.

Regular scrutiny of your credit report not only helps in verifying the accuracy of information recorded under your name but also aids in early detection of possible fraud or identity theft.

Tips for Maintaining a Healthy Credit Score

Once you gain access to your credit score and report, the next logical step is to strategize how to maintain or improve your credit health. A healthy credit score is reflected through consistent, responsible credit management which involves several key practices:

1. **Credit Utilization**: Aim to keep your credit utilization ratio below 30%. This practice involves maintaining a balance between your credit limits and the amounts you owe.

2. **Timely Bill Payments**: Ensure you’re paying your bills on time. Late payments can have a significant negative impact on your credit score.

3. **Avoid Excessive Debt**: Resist the temptation to carry large balances across multiple accounts. Managing fewer debts demonstrates financial responsibility.

4. **Regular Monitoring**: Continuously check your credit score and report. Regular monitoring helps in quickly identifying inaccuracies or fraudulent activities, allowing prompt corrective actions.

Through disciplined financial habits and leveraging the free resources available to monitor your credit, you can effectively manage your credit health, achieve your financial goals, and enjoy peace of mind.
The benefits of keeping a credit card open for a long time

The benefits of keeping a credit card open for a long time

The Impact on Credit Score

Managing a credit card effectively has many implications for your financial health, particularly concerning your credit score. Keeping a credit card open over an extended period can have a constructive impact on your credit report, primarily because credit scoring models, like those employed by the major credit bureaus, indeed regard the length of your credit history significantly in their calculations. A prolonged credit history serves as an indicator of stability and responsible credit management, presenting a positive image to potential lenders.

Average Age of Accounts

A critical component of your credit history is the average age of your credit accounts. Opening new accounts frequently or closing existing ones can lower this average age. Therefore, maintaining an open credit card can enhance the average age of your accounts. This is particularly relevant as credit history length contributes to approximately 15% of your overall credit score, demonstrating its significance in the broader credit scoring model. By allowing accounts to age, you present a stable financial portrait to credit assessors.

Credit Utilization Ratio

The credit utilization ratio is another pivotal factor impacting your credit score. Essentially, this ratio reflects the proportion of your credit in use compared to the total credit available to you. By keeping credit cards open and maintaining a low balance relative to your credit limit, you effectively lower your credit utilization ratio. A reduced ratio is viewed favorably by lenders because it suggests that you are not reliant on credit to manage your finances, but rather use it judiciously, which portrays financial prudence.

Maintaining a Diverse Credit Mix

Having a varied credit mix is advantageous as well in credit scoring. Credit scoring models typically prefer a balance of credit account types, including both installment loans and revolving credit accounts such as credit cards. By keeping a credit card open, you contribute to this diversity, demonstrating to lenders that you have experience and capability in managing different types of credit products responsibly. This diversity enriches your credit profile, potentially leading to more favorable assessments by lenders when evaluating credit applications.

Potential Cost Savings

Beyond credit scoring, leaving a credit card open could yield cost-saving opportunities. Numerous credit cards offer reward schemes, including cashback, travel points, or special discounts. By keeping an account open, you enable persistent access to these benefits, assuming wise use and timely repayment of balances to prevent incurring interest charges. Over time, these rewards can accumulate to significant savings, effectively reducing the costs associated with maintaining credit cards.

Avoiding Negative Implications

Closing a credit card, especially one with a long-standing history, might negatively affect your credit profile by reducing your total available credit, consequently elevating your credit utilization ratio. Furthermore, closing accounts can lower the average age of your credit accounts, affecting the length of your credit history adversely. It’s prudent to weigh these potential impacts carefully. For readers seeking more comprehensive guidance on managing credit cards to sustain a robust credit score, resources from financial institutions or credit counseling services can offer valuable insights.

Conclusion

To conclude, keeping a credit card open for a long duration can be beneficial on multiple fronts. It can have a positive effect on your credit score, contribute to a diversified credit mix, and also potentially offer economic rewards. Responsible credit card management is imperative, as strategic oversight of credit card accounts has far-reaching implications for your overall financial well-being. For those eager to delve deeper into credit score improvement and maintenance strategies, exploring resources from financial experts or credit bureaus would be advantageous. Engaging with such materials can enhance understanding and enable informed financial decisions in managing personal credit health.

How to close a credit card account without affecting your credit

How to close a credit card account without affecting your credit

Understanding the Impact of Closing a Credit Card

Closing a credit card account is a significant financial decision that can have various implications, particularly for your credit score. It’s essential to understand how this act can alter your credit profile. The primary areas of concern when closing a credit card are its effects on your credit utilization ratio and the average age of your credit accounts. Grasping these concepts is crucial for making informed decisions about your credit health.

Credit Utilization Ratio

The credit utilization ratio is one of the most critical components of your credit score. It refers to the amount of credit you are using relative to your total available credit. Ideally, maintaining this ratio below 30% is recommended to preserve a healthy credit score. For instance, if your total credit limit across multiple cards is $10,000, you should aim to keep your credit usage below $3,000. When you close a credit card account, you reduce your overall available credit. This can inadvertently increase your utilization percentage if there are existing balances on other cards, potentially leading to a lower credit score.

Average Age of Credit Accounts

Another key factor in your credit score calculation is the average age of your credit accounts. The average age takes into account all your active credit lines and can significantly influence your creditworthiness. The older your credit history, generally, the more favorable it is perceived by lenders. Consequently, closing a credit account, especially an older one, can decrease the average age of your accounts, possibly impacting your credit score negatively. Therefore, it’s wise to retain older accounts open when feasible, as long as they do not incur large fees or unmanageable terms.

Steps to Close a Credit Card Account Wisely

If you decide that closing a credit card is the best course of action for your financial situation, there are certain steps you should follow to minimize any adverse effects.

Ensure a Zero Balance

Before closing the card, it’s imperative to ensure the account balance is fully paid off. A zero balance is essential to prevent any future interest charges or fees that might accrue after the account closure. It also simplifies the closure process and ensures financial peace of mind.

Use Remaining Rewards

Many credit cards offer rewards such as cash back, points, or travel miles. Before initiating the closure of a card, it is prudent to redeem these rewards. Failure to do so usually results in the forfeiture of unused rewards once the account is sealed. Thus, redeeming the rewards ensures you receive the benefits you’ve earned without loss.

Contact the Card Issuer

Once you’ve settled the balance and utilized the rewards, the next step is to contact the card issuer directly. Use the customer service number found on the back of the card to request account closure. During this conversation, confirm that the account is being closed with a zero balance. For your records, request a confirmation number or an official email confirming the closure.

Monitor for Any Remaining Charges

After the closure, vigilance is crucial to ensure that no residual charges appear. Regularly monitor your email and account statements to verify that all transactions are honored and no automated payments or pending transactions occur post-closure. Keeping tabs on this can prevent unexpected debt from reappearing.

Alternatives to Closing a Credit Card

If you are concerned about potential negative effects on your credit score from closing an account, there are alternative courses of action you can consider that may align better with your financial goals.

Downgrade the Card

Many card issuers provide an option to downgrade your card. This involves retaining the account while switching to a version with no annual fee or altered terms that might better suit your current financial situation. This method helps maintain account age and credit line availability without incurring ongoing fees.

Keep the Card for Occasional Use

Another viable alternative is to retain the card for occasional use, particularly if it has no annual fee. By making small purchases periodically and paying off the balance immediately, you can keep the account active. This practice helps preserve your credit history and score, providing a manageable and convenient way to maintain financial flexibility without accumulating additional debt.

In considering whether to close a credit card or explore alternative options, it is essential to review your personal financial situation and future plans carefully. The choices you make regarding your credit cards can significantly affect your credit health and overall financial stability. Remember to weigh the pros and cons of each option and consult financial advisors if needed to make informed decisions.

For more in-depth financial tips and guidance, please visit our website.

How to use a credit card for recurring payments

How to use a credit card for recurring payments

Understanding Recurring Payments

Recurring payments are a significant element of modern financial management, particularly convenient in our fast-paced world. They involve the automatic deduction of funds from a credit card at regular, predefined intervals, generally monthly. This method is prevalent for managing payments related to subscriptions, memberships, or essential services such as utilities. When managed appropriately, these payments can not only simplify the payment process but also support effective personal budgeting strategies.

Choosing the Right Credit Card

Selecting an appropriate credit card is crucial when engaging with recurring payments. A vast array of credit cards exist, each offering distinct advantages tailored to varied spending behaviors. When choosing a card, it is beneficial to assess which one aligns with your spending habits and financial goals. Many credit cards provide added incentives for recurring payments, such as cash back or reward points. These incentives can accumulate over time, providing tangible benefits back to you. Moreover, it is advantageous to choose a card that features a sufficient credit limit. This ensures that you can comfortably manage and cover your monthly charges without risking maxing out your card.

Setting Up Recurring Payments

Embarking on the process of setting up recurring payments with your chosen credit card is straightforward and involves several key steps:

  1. Initially, get in touch with the service provider to whom you will be making payments. Discuss your intention to charge payments automatically to your credit card.
  2. Next, you will be required to provide essential credit card details. This typically includes the card number, expiration date, and the CVV (Card Verification Value), which is a security feature for online transactions.
  3. Lastly, ensure that you clearly understand and verify the payment interval. This involves confirming that the recurring payment schedule aligns with your personal billing cycles, which helps in preventing any unexpected deductions.

Upon approval from the relevant service provider, the organization will then proceed to automatically debit the specified amount from your credit card at the agreed intervals.

Managing and Monitoring Payments

Effective management and diligent monitoring of your recurring payments are essential to maintaining accuracy and avoiding potential pitfalls. Regularly analyzing your credit card statements plays a significant role in this process. Here are several strategies to manage these payments effectively:

  • Check Statements: This is a crucial step where you should routinely review your credit card statements. This practice enables you to verify each charge, ensuring that only authorized transactions are being debited and helping to quickly identify any discrepancies.
  • Set Alerts: A number of credit card providers offer the useful feature of automated alerts. These alerts can notify you of upcoming payments due or when transactions are completed. This service proves invaluable in tracking your recurring expenses and maintaining an overview of your financial status.

Handling Changes and Cancellations

Occasionally, you might find it necessary to modify or cancel a recurring payment. Addressing these changes requires a structured approach:

  1. Begin by contacting the relevant service provider. Whether you wish to update your payment information or terminate the service entirely, clear communication with the provider is essential.
  2. Following this, confirm these changes with your credit card issuer. This step ensures that the automatic payment has been updated or discontinued as per your request. It is vital for maintaining the integrity of your financial records.

As a best practice, it is advisable to document all communications with service providers. Keeping records not only acts as a reference for future inquiries but also can serve as proof in case of any disputes.

Protecting Your Financial Information

The convenience of using a credit card for recurring payments is accompanied by the responsibility of safeguarding your financial details. Employing certain measures can help protect your sensitive information from unauthorized access:

  • Monitor Transactions: Regularly check your account activity to ensure that all transactions are authorized. This practice serves as an immediate red flag for any unauthorized or suspicious activity that might occur.
  • Use Secure Networks: Conduct any access to your financial data over secure internet connections. This reduces the risk of your information being intercepted by malicious entities online.
Conclusion

Incorporating a credit card into your routine financial management for recurring payments can significantly streamline how you handle your monetary obligations. Not only does this method simplify the logistics of managing payments and interactions with service providers, but it also offers the potential to accrue rewards over time. Ensuring the proper setup of these payments, coupled with consistent monitoring and safeguarding of your financial details, can lead to efficient and worry-free financial management. For more in-depth advice on credit card management and financial planning, consider exploring resources such as NerdWallet or Bankrate.

The importance of comparing credit card fees before applying

The importance of comparing credit card fees before applying

Understanding Credit Card Fees

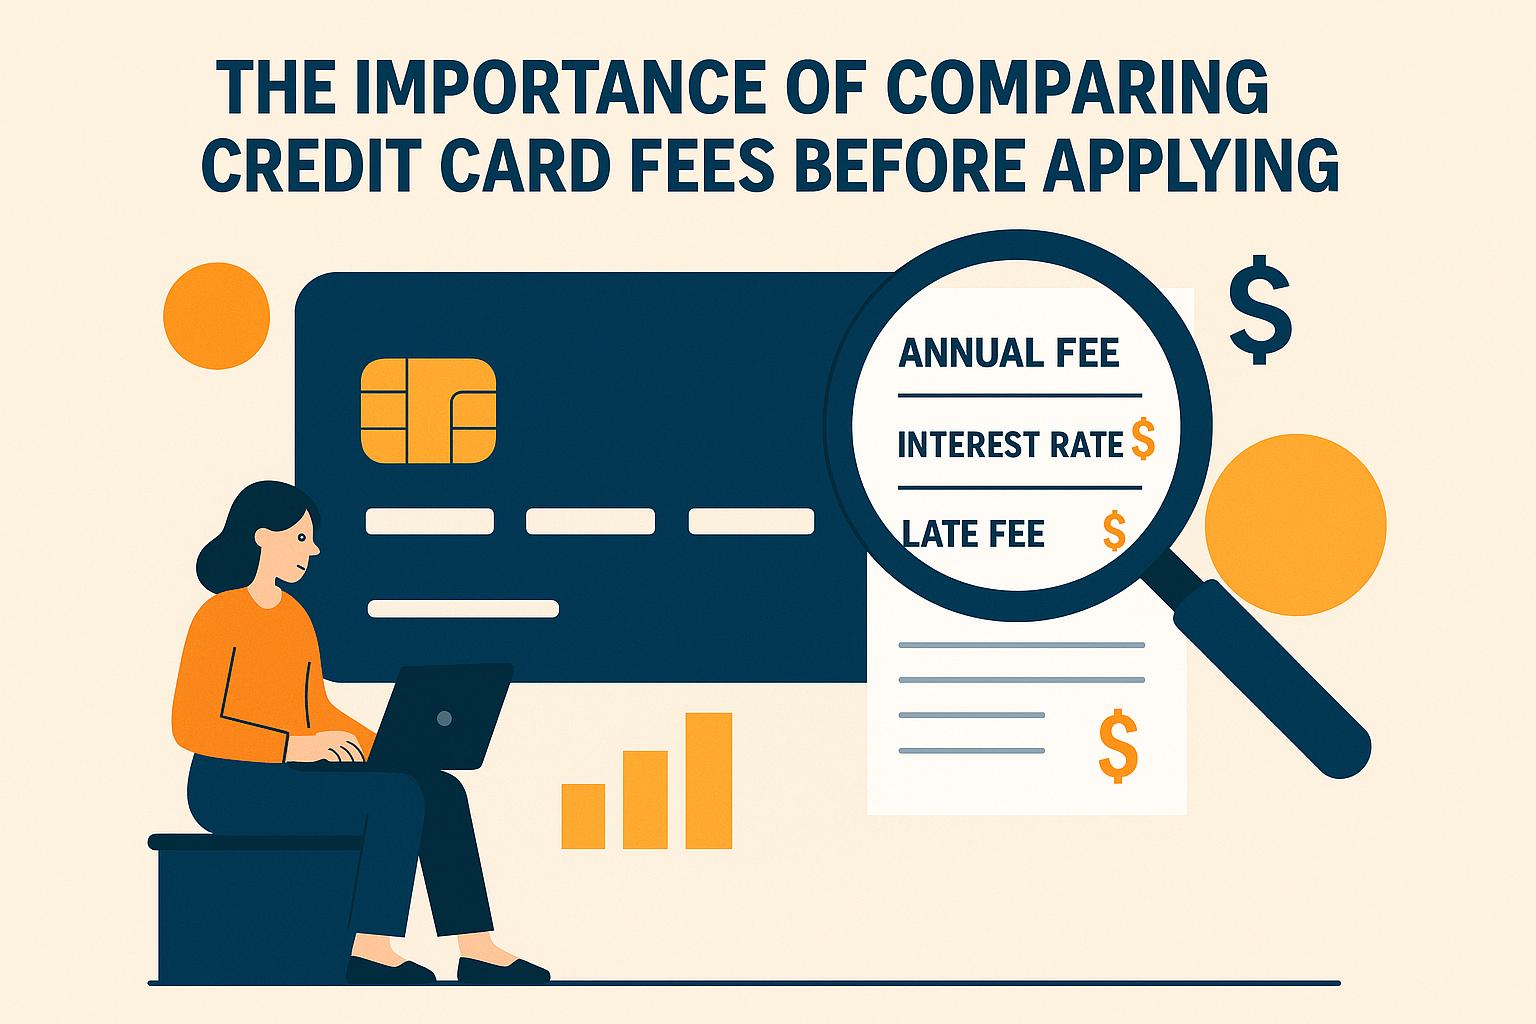
When applying for a credit card, it’s crucial to understand the various fees that may apply. These fees can significantly impact the total cost of using a credit card, often making what seems like a good deal more expensive over time. Taking the time to compare credit card fees can help you avoid unexpected charges and make a more informed financial decision.

Types of Credit Card Fees

Credit card fees come in several forms, each affecting your financial experience in different ways. Let’s delve deeper into the different types of fees that are commonly associated with credit cards.

Annual Fees: Many credit cards charge an annual fee merely for the privilege of holding the card. This fee can vary greatly from one card to another, ranging from zero to several hundred dollars. Some credit card issuers waive this fee for the first year, providing an initial incentive to attract new customers. However, it’s important to consider how the fee aligns with the benefits provided by the card.

Interest Rates: While not a fee in the traditional sense, the interest rate is a pivotal factor that significantly impacts the overall cost of carrying a balance on a credit card. Suppose you don’t pay off your balance in full each month. In that case, a higher interest rate can lead to substantial additional charges. Understanding the annual percentage rate (APR) and how it applies to different types of transactions, such as purchases, balance transfers, and cash advances, is vital.

Late Payment Fees: Credit card companies often charge a late payment fee if you miss a payment or fail to pay at least the minimum amount by the due date. These fees can be quite hefty, and repeated late payments not only burden you with extra charges but also have negative implications for your credit score. Maintaining a good payment history is essential for keeping borrowing costs low and preserving creditworthiness.

Foreign Transaction Fees: If you use your credit card to make purchases in a foreign currency or while traveling internationally, many banks will impose a foreign transaction fee. This fee is typically a percentage of the transaction, often between 1-3%, which can add up if you frequently travel or purchase from international vendors. Choosing a card with no foreign transaction fees can result in significant savings for globetrotters.

Promo Rates and Other Charges

Credit card offers can sometimes come with enticing promotional rates. These promotions, such as 0% interest for a specified period, can provide substantial savings initially. However, it’s crucial to understand what the rate will be once the promotional period concludes. Missing payments or carrying a balance past this period can lead to high-interest charges.

Additionally, be aware of balance transfer fees. While transferring a balance can help consolidate debt, fees for doing so may offset the savings from lower interest rates. It’s also important to consider cash advance fees, which apply when you use your credit card to withdraw cash. These fees, along with the typically higher interest rates for cash advances, make them an expensive option.

Penalties for exceeding your credit limit are another critical consideration. Some cards may impose fees if you go over your credit line, while others may simply decline transactions. Understanding your card’s terms and how limits are enforced can prevent unnecessary expenses.

Comparing Credit Card Offers

When comparing credit cards, it’s imperative to scrutinize the terms and conditions for all fees and charges. Many banks and financial institutions provide this information on their websites, making it easier for consumers to make comparisons. Some websites also offer tools that allow you to compare credit card offers side by side, highlighting key differences such as fees and interest rates.

Evaluating credit card offers involves more than just comparing fees. Consider the rewards and benefits, such as cashback, travel miles, or points, which might offset some of the costs. Also, explore the card’s compatibility with your lifestyle and spending habits.

The Importance of Reading the Fine Print

No matter how attractive a credit card offer may seem, always read the fine print to ensure you understand all potential costs. Hidden fees and charges often lurk in the details and can impact your financial situation. Understanding these terms enables you to make informed choices.

Moreover, keep in mind that introductory offers often have terms that require you to meet specific criteria, such as spending a certain amount within a given timeframe to earn rewards bonuses. Not meeting these criteria can affect the overall value of the card.

Taking the time to understand and compare credit card fees can help you select the right card for your needs. By doing so, you can avoid unnecessary expenses and ensure that your credit card works for you, not against you. Whether you’re a frequent traveler, a dedicated shopper, or someone building credit, choosing the right card requires a prudent evaluation of costs and benefits.

In conclusion, understanding credit card fees empowers you to make sound financial decisions. With careful consideration and comparison, you can maximize the benefits of your credit card while avoiding unexpected charges that could affect your financial well-being.

What is a charge card, and how does it differ from a credit card

What is a charge card, and how does it differ from a credit card

Understanding Charge Cards

Charge cards are a distinctive type of payment card that enable you to make purchases and settle the payment in full at the end of each month. Unlike traditional credit cards, charge cards do not have a predetermined credit limit. This can offer greater flexibility, but it comes with the responsibility of paying the balance in full when the due date arrives.

How Charge Cards Work

The fundamental operation of charge cards involves the requirement for the cardholder to pay off the entire balance each month. If the cardholder fails to do so, it often results in a significant late fee and might adversely affect their credit score. The mandatory monthly payoff of the balance means charge cards are typically less susceptible to debt accumulation compared to credit cards. As a consequence, they can be beneficial for those seeking to avoid the pitfalls of debt that might arise from revolving credit.

Key Distinctions Between Charge Cards and Credit Cards

Credit Limit

Charge Cards: They usually do not come with a specified credit limit. This absence of a set limit allows cardholders to spend in a way that aligns with their income and spending habits. However, this flexibility comes with the obligation to manage one’s finances proficiently.

Credit Cards: In contrast, credit cards are issued with a designated credit limit. This specified limit dictates the maximum amount that cardholders can spend. Spending beyond this limit might lead to incurred fees or declined transactions, serving as a boundary for financial planning.

Payment Requirements

Charge Cards: These cards require the full balance to be cleared every month, thereby preventing the accrual of debt since the balance cannot be carried over to the following month.

Credit Cards: Offer cardholders the option to make minimum payments. This means that the remaining balance can roll over month to month, often incurring interest on the unpaid amounts. This provides greater short-term flexibility at the potential cost of accruing interest.

Interest Rates

Charge Cards: Generally, they do not charge interest, given that balances must be paid in full each month. This aspect is beneficial for those looking to avoid interest fees altogether.

Credit Cards: Typically, they charge interest on any overdue balance after the grace period. This interest can compound, potentially increasing the total amount owed significantly if not managed wisely.

Pros and Cons of Charge Cards

Pros

Spending Flexibility: Without a preset spending limit, charge cards can offer spending flexibility that’s tailored based on the cardholder’s usage and repayment history.

Interest-Free Usage: Since there are no residual balances, users can entirely avoid interest charges by following the payment guidelines.

Cons

Full Payment Requirement: The necessity to clear the entire balance each month may pose a challenge for some. This requires disciplined financial management, as there’s no option to carry over some of the balance to the next month.

Limited Availability: Unlike credit cards, charge cards are not as widespread and the criteria for approval can be more stringent. This might make them less accessible to a broader audience.

Conclusion

Both charge cards and credit cards serve the primary purpose of facilitating transactions, but they cater to different financial preferences and strategies. Charge cards are tailored for disciplined spenders who can manage to pay off their balance monthly. This lack of interest charges can be attractive to some users. On the other hand, credit cards offer more flexibility with the option to carry a balance from one month to the next, though this comes with the potential cost of incurring interest fees. It’s essential to understand these differences to select the right financial tool that aligns with your spending habits and financial management goals.

Another consideration is the rewards programs that many credit and charge cards offer. Although not universal to all charge cards, some do provide enticing reward structures, allowing users to accumulate points or cash back based on their spending. These rewards can be an additional benefit for those who diligently pay off their balances each month.

Additionally, it’s worth noting the impact of these cards on your credit score. Regular and responsible use of a charge card, with timely full payments, can boost your credit score over time. However, missing payments or failing to settle the balance can conversely lead to penalties and a decrease in your creditworthiness.

Choosing between a charge card and a credit card depends largely on personal fiscal discipline and the ability to pay off balances routinely. For individuals who are accustomed to maintaining a stricter budget and can predict and cover their monthly expenditures without carrying a balance, a charge card could be beneficial. Such individuals can leverage the absence of credit limits while avoiding interest charges.

In contrast, those who prefer the flexibility of carrying a balance and appreciate the option of spreading expenses over several months might lean towards credit cards. These cards can be particularly useful for managing cash flow inconsistencies or larger expenses that require distribution over an extended period.

It is also essential for potential cardholders to consider the fees associated with these cards. Many charge cards carry annual fees, which might not always be justified unless the cardholder fully utilizes the associated benefits and rewards. Thus, a careful analysis of the related costs and advantages is crucial.

Furthermore, the prestige associated with some charge cards, often seen as a status symbol, holds value for some consumers. They often come with premium benefits, including personalized customer service or access to exclusive events, which can enhance the cardholder’s experience beyond the realm of regular transactions.

In conclusion, understanding the unique features and requirements of both charge cards and credit cards enables cardholders to make informed decisions that align with their financial preferences and responsibilities. Whether you value the disciplined approach of a charge card or the flexibility of managing rolling balances via a credit card, knowledge is the key to maximizing the benefits and rewards these financial tools offer.

The impact of credit card inquiries on your credit score

The impact of credit card inquiries on your credit score

The Impact of Credit Card Inquiries on Your Credit Score

When it comes to managing your credit score, a clear understanding of the various actions that impact it is crucial. Specifically, credit card inquiries play a significant role in shaping your credit story. Lenders perform these inquiries when they review your credit history prior to approving a new line of credit or a loan. Though these inquiries are a normal part of the borrowing process, it’s important to recognize their varying impacts on your overall credit score.

Types of Credit Inquiries

Credit inquiries fall into two main categories: hard inquiries and soft inquiries. Knowing the distinction between the two can help you better manage your financial habits.

Hard inquiries occur when a financial institution reviews your credit report to make lending decisions. Common scenarios include applying for a new credit card, a mortgage, or an auto loan. Because these inquiries imply you are seeking additional credit, they have the potential to impact your credit score negatively. Each hard inquiry might slightly reduce your score, although the effect is seldom more than a five-point drop.

Conversely, soft inquiries do not affect your credit score. These come into play when you check your own credit score or when a lender conducts a pre-approval check for a loan or credit card without your request. Additionally, existing creditors may review your report now and then, all categorized under soft inquiries. Such inquiries are visible only to you and are not accessible to potential lenders.

How Hard Inquiries Affect Your Credit Score

In the realm of credit score calculations, hard inquiries account for approximately 10% of the total score, contributing to what is labeled as “new credit.” While a single inquiry usually has a minimal effect, reducing your score by less than five points, accumulating several inquiries over a short period can considerably influence your score.

Time Frame and Deduplication

When shopping for particular loans such as mortgages, auto loans, or student loans, multiple inquiries within a condensed period are often treated as a singular inquiry. This principle is known as deduplication and applies within 14 to 45 days, depending on the scoring model in use. Deduplication allows prospective borrowers to search for optimal rates without causing a disproportionately negative impact on their credit scores.

Duration of Impact

The effect of hard inquiries on your credit score is not everlasting. Although they remain on your credit report for up to two years, their influence is typically limited to the first 12 months. As time passes, the impact lessens, gradually fading from its initial significance.

Best Practices to Manage Credit Inquiries

While hard inquiries are an element of maintaining healthy credit usage, it is wise to limit new credit applications. Here are some practical guidelines for managing inquiries effectively:

Be Selective in Applications: Before applying for new credit, assess your needs carefully. Conduct thorough research to ensure you target your applications to lenders or areas that match your current financial goals and requirements.

Timing for Rate Shopping: When searching for loans, aim to conduct your rate comparisons within a condensed time period. This approach minimizes the impact of hard inquiries by leveraging deduplication.

Regular Credit Report Reviews: Monitor your credit report periodically to verify the accuracy of the inquiries recorded. This practice ensures you remain aware of your credit standing and can confirm all inquiries are legitimate, offering you peace of mind and control over your financial health.

Obtaining additional information and guidance on effective credit management can further empower you to maintain or improve your credit health. Visiting resources like Experian and Equifax can provide you with valuable insights and tools to enhance your knowledge and application of credit management strategies.

In conclusion, awareness of how credit inquiries impact your credit score is essential for making informed financial decisions. By applying the principles and practices outlined, you can confidently navigate the credit landscape, ensuring your actions positively influence your credit profile over time.

How to use credit cards to earn travel benefits

How to use credit cards to earn travel benefits

The Basics of Earning Travel Benefits with Credit Cards

When used strategically, credit cards can be a powerful tool for earning travel benefits. By understanding how to leverage features such as rewards programs, sign-up bonuses, and travel perks, you can significantly reduce your travel costs and even enjoy luxury experiences for less.

Understanding Rewards Programs

Many credit cards offer rewards programs that allow you to earn points or miles for every dollar spent. These points can often be redeemed for travel-related expenses, such as flights, hotel stays, and car rentals. It is essential to choose a credit card with a rewards program that aligns with your spending habits and travel goals.

Key Points to Consider:

Types of Rewards: There are different types of reward systems offered by credit cards. Some cards provide points, while others accumulate airline miles or hotel points. It is crucial to determine which type aligns best with your travel preferences. For instance, if you are a frequent flyer with a particular airline, a card that earns airline miles might be more beneficial. On the other hand, if you prefer flexibility in your travels, opting for a card that earns more general points could provide you with varied redemption opportunities.

Redemption Options: When considering a rewards program, it’s important to review how flexible the redemption options are. Ideally, you should choose a program that allows you to use points for a variety of travel expenses. The most versatile programs might let you redeem points for flights, hotel stays, car rentals, or even experiences and excursions. Look for any restrictions on redemptions, such as blackout dates, as these could limit your ability to use your rewards when you want to.

Maximizing Sign-Up Bonuses

Many credit cards offer sign-up bonuses that can provide a significant boost to your points balance. These bonuses usually require you to spend a certain amount within the first few months of opening the card.

Tips for Maximizing Bonuses:

One primary strategy to maximize bonuses without incurring debt is ensuring you can meet the required spending threshold comfortably. Planning your application to align with upcoming major purchases can be particularly beneficial. For example, if you plan to make renovations in your home or have large business expenses, timing your credit card application to coincide with these purchases can help you meet bonus thresholds effortlessly. Always ensure that you can meet these requirements without straying into impractical financial decisions.

Time your application to align with major purchases or expenses to meet the spending requirement effortlessly. This strategic approach not only maximizes your bonus potential but helps integrate the spending into your budget without causing unnecessary financial strain.

Leveraging Travel Perks

Aside from earning points and miles, many travel credit cards offer additional travel benefits that enhance the overall travel experience. These may include airport lounge access, travel insurance, and priority boarding.

Consider These Additional Perks:

Airport Lounge Access: One valuable perk often provided by travel credit cards is access to airport lounges. These lounges offer a comfortable and calm environment in contrast to busy airport terminals. Amenities can include complimentary snacks and beverages, Wi-Fi, and quiet spaces to relax or work.

Travel Insurance: Another critical benefit of travel credit cards is travel insurance, which provides essential security against unforeseen travel disruptions. This may cover aspects like trip cancellations, lost luggage, or medical emergencies while traveling, offering peace of mind as you journey.

Priority Boarding: Priority boarding is another convenient perk that can make your travel experience more enjoyable. It typically allows you to board the plane ahead of most passengers, meaning you can secure space in overhead bins for your luggage and settle in sooner.

Strategies for Earning More Points

To maximize the travel benefits offered by your credit card, employ strategies that increase your points accumulation without increasing your spending unnecessarily. For instance, many cards provide extra points for certain categories, such as dining, travel, or groceries.

You can use your card strategically in these bonus categories to earn more points. Pay attention to any promotions your card provider offers where you can earn additional points, such as seasonal promotions or partnerships with specific retailers.

To further enhance your earning potential, consider combining credit card rewards with loyalty programs of airlines or hotels. Many credit cards affiliated with airline or hotel chains offer higher point accumulations when spending is done with those entities.

Be Mindful of Fees and Interest Rates

While travel credit cards offer excellent benefits, they often come with high annual fees and interest rates. Ensure the value you gain from rewards and perks exceeds the costs associated with the card.

Paying off your balance in full each month is vital to avoid interest charges, which can quickly outstrip the value of any rewards you’ve earned. Consider opting for a card with no foreign transaction fees if you travel internationally frequently.

Conclusion

By understanding the features and benefits travel credit cards offer, you can turn your everyday spending into a powerful tool for earning travel benefits. With strategic use and careful management, credit cards can play a significant role in making your travel more affordable and luxurious. Whether you’re looking for opportunities to experience new destinations or to travel in more comfort, using credit cards responsibly allows you to unlock numerous benefits. For more detailed tips and recommendations on specific cards, consider visiting dedicated financial advice websites like NerdWallet or The Points Guy to find the best card for your needs. These resources provide valuable insights and up-to-date information that can assist in making the most informed decision for your travel needs and financial situation.

The difference between rewards points and travel miles

The difference between rewards points and travel miles

Understanding Rewards Points and Travel Miles

Rewards points and travel miles have become an integral part of financial and travel strategies, predominantly offered by credit card companies and airline loyalty programs. These incentives are designed to encourage customer engagement and spending by providing tangible benefits. While both rewards points and travel miles aim to enhance user experience and offer substantial rewards, there are critical differences in how they accumulate, how they can be redeemed, and their overall value. Understanding these differences is essential for consumers who seek to maximize the benefits from these loyalty programs.

Accrual Mechanisms

Rewards Points: Rewards points are typically accumulated through everyday purchases made with a credit card. Major financial institutions offer various rewards cards, each with different accrual rates linked to categories of spending such as groceries, dining, or fuel. Some credit cards might have partnerships with specific brands or retailers, providing bonus points for shopping within these networks. This system encourages consumers to integrate their credit cards into their daily transactions, gradually accruing points that can later be redeemed for various rewards.

Travel Miles: Travel miles, also known as frequent flyer miles, are primarily earned through air travel with a specific airline or a consortium of airlines that form an alliance. Passengers accumulate miles based on the distance traveled, the class of service, and sometimes the fare paid. Additionally, airlines often partner with credit card issuers to offer co-branded cards that allow users to earn miles not only on flights but also on other purchases. In such cases, additional incentives might be introduced to earn more miles on travel-related expenses, creating a comprehensive travel-centric rewards strategy.

Redemption Options

Rewards Points: One of the key advantages of rewards points is their broad range of redemption options. These points can be exchanged for diverse items including gift cards, electronics, and cash back. Many programs provide an online portal or app where users can easily browse and select options for redeeming their accumulated points. Travel-related purchases, such as booking flights, hotels, or car rentals, are often available, allowing users to leverage their points to offset travel costs. Some rewards programs also provide exclusive experiences, from concert tickets to curated travel packages, which might offer greater value in point redemption.

Travel Miles: The redemption of travel miles is typically focused on enhancing the travel experience. Miles can be used to book flights, seat upgrades, and other airline services. This offers travelers significant savings, especially when miles are used for premium cabins or long-haul flights. Airlines typically have a dedicated section on their websites for booking award travel, where travelers can seamlessly utilize their miles. Additionally, some programs allow miles to be transferred to partner hotel loyalty programs or used for ancillary travel-related costs. However, the flexibility in how miles can be redeemed often varies by airline, with some providing more varied options than others.

Value Considerations

Rewards Points: The value of rewards points can vary based on how they are redeemed. For instance, using points for statement credits or online shopping might offer less value per point compared to redeeming them for travel-related purchases or exclusive experiences that the program might offer. Therefore, it is critical for users to carefully review the terms and conditions of their rewards program to ensure they are achieving maximum value. Calculating the cost-benefit ratio of different redemption options can help users optimize their strategy and derive the most benefit from their points.

Travel Miles: The value of travel miles is often more complex to ascertain, as it is influenced by several factors, such as flight availability, class of travel, and destination. Generally, miles offer better value when used for premium class travel or international destinations. This is due to the higher cash value of these tickets, which translates to more value per mile. However, users need to be aware of potential pitfalls, such as restrictions or blackout dates, which airlines might enforce on award travel. Being strategic about booking can ensure travelers extract the most value from their miles.

Additional Differences

Beyond accrual and redemption, both rewards points and travel miles come with nuances that can affect a consumer’s strategy. Many programs set expiration dates for points and miles, necessitating a prompt approach to redemption to prevent the loss of accumulated rewards. Additionally, certain programs might impose fees for specific redemption actions or for maintaining an account, which can impact the overall benefit derived from the program. Staying informed about such terms is crucial for maximizing the benefits of these loyalty offerings.

In weighing the benefits and deciding between rewards points and travel miles, consumers can expand their understanding through detailed comparisons and expert advice. Trustworthy financial websites like NerdWallet or The Points Guy provide valuable insights. By understanding the distinctions and value propositions of rewards points and travel miles, consumers can tailor their spending strategies to optimize their returns, ultimately enhancing their financial and travel experiences significantly.

What is a cashback credit card, and how does it work

What is a cashback credit card, and how does it work

Understanding Cashback Credit Cards

A cashback credit card is a unique financial tool that offers cardholders monetary rewards based on their spending habits. By understanding how these cards work, you can make informed decisions that optimize your earning potential and align with your financial objectives. These rewards come back to you as a percentage of each purchase you make, effectively reducing your costs over time. By using this rewarded cash, you could either reduce your credit card balance or transfer it to a savings account.

How Cashback Credit Cards Work

The fundamental principle of a cashback credit card involves earning a certain percentage of your expenditures back as cash rewards. Each transaction adds to your cashback, which you can accumulate over time. Based on the cardholder agreement, the percentage of cashback may vary. For instance, certain cards might reward you more for purchases in categories like groceries, dining, and fuel. It’s important to recognize these categories as they can significantly influence the amount of cashback you earn.

Example: If you own a cashback credit card that offers 2% back on grocery expenses and you spend $200, you’ll receive $4 back as cashback. This simple transaction shows how your regular purchases can turn into savings over time.

Types of Cashback Offers

The landscape of cashback offers is diverse, catering to various spending habits and preferences. These offers can be categorized into several types:

Flat-rate cashback: This type of card provides a fixed cashback rate on all purchases. They are highly advantageous for their straightforwardness, offering a consistent cashback percentage regardless of the spending category. They are ideal for those who prefer simplicity and do not wish to track rotating categories or targeted spending specifics.

Tiered cashback: These cards are structured to provide varying cashback percentages based on spending types. For example, you might earn 3% on dining, 2% on groceries, and 1% on other purchases. This structure is appealing for individuals with predictable spending habits in particular categories. By focusing your spending in higher reward categories, you maximize the benefits effectively.

Rotating categories: Some cards are designed to maximize benefits in certain categories that change periodically. Typically updated every quarter, cardholders must actively enroll or opt-in for these categories to receive the heightened cashback. This option is beneficial for those who enjoy optimizing their spending and adapting to seasonal promotions to earn more.

Redeeming Cashback

Once you have accrued cashback, the next step is redemption. While the process may vary from card to card, it usually includes several common redemption methods:

– Statement credits: This option allows you to apply your cashback earnings directly to your credit card balance, effectively lowering your outstanding bill.
– Direct deposits: You can choose to transfer the cashback amount to your bank account, making it readily available for other financial needs.
– Cheques: Some card providers offer the option to have a cheque mailed to you, representing another accessible way to utilize your cashback.
– Gift cards or merchandise: In certain scenarios, you may redeem cashback for gift cards or select products offered by the credit card company.

Familiarizing yourself with your credit card’s redemption policies is essential, as minimum redemption thresholds or specific conditions might apply. This understanding ensures you extract the maximum value from your earnable cashback.

Benefits and Considerations

The utilization of a cashback credit card can bring several advantages. Foremost, cardholders gain the opportunity to earn a percentage back on daily expenses, effectively reducing overall costs. This accumulated cashback could translate into significant savings and better resource allocation over time. Moreover, they provide the satisfaction of redeeming financial rewards that can bolster savings or enable various purchases.

However, obtaining a cashback credit card involves certain considerations. For instance, it’s essential to analyze the card’s annual fees and interest rates to ensure the rewards outweigh any potential costs. Additionally, be aware of any spending limits imposed on cashback rewards, which could cap your potential earnings. These factors might influence the overall value and benefit derived from using the cashback credit card.

To make an informed choice, assess your individual spending habits and financial goals. Evaluate whether this type of card aligns with your needs, taking into account not only the rewards but also the costs and features. Access to additional resources, such as detailed comparisons and user reviews, can provide insight into available cashback cards and their suitability for your lifestyle.

In conclusion, cashback credit cards offer an appealing approach to earn money on routine expenditures. By selecting the right card and maximizing its offerings, you can enhance your financial strategy while enjoying returns on your regular spending. The dynamic structure of these cards allows for a customizable fit to your purchasing habits, ultimately guiding you towards prudent financial management.